
Running short of money before payday can be stressful, especially when an unexpected bill cannot wait. A medical expense, urgent car repair, overdue utility bill, or essential household purchase may leave you searching for a fast cash loan now.
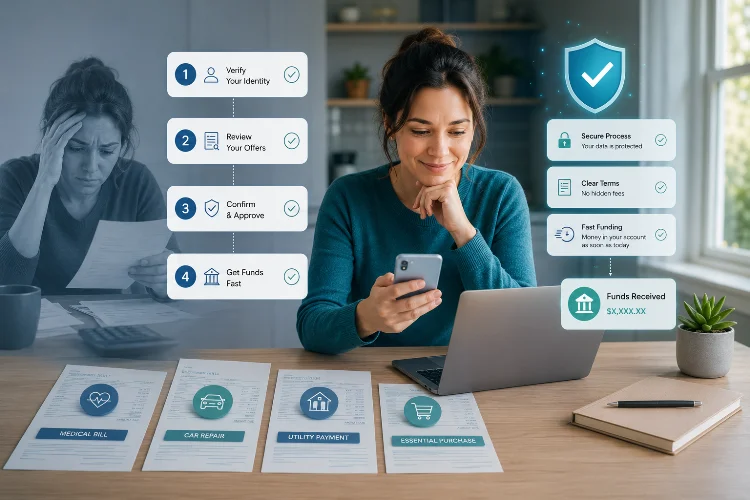
Online lenders have made the application process quicker and more convenient than traditional in-person borrowing. In many cases, borrowers can complete a form, verify their information, review a loan offer, and receive funds without visiting a physical office.
However, speed should not be the only consideration. Fast loans can carry expensive fees, short repayment periods, and strict withdrawal terms. Before applying, it is important to understand how these loans work, how much they may cost, and whether a less expensive alternative is available.
What Is a Fast Cash Loan?
A fast cash loan is a small, short-term loan designed to cover an immediate financial need. Depending on the lender, it may be marketed as a payday loan, cash advance, emergency loan, same-day loan, short-term installment loan, or no-fax loan.
Traditional payday loans are generally for relatively small amounts and are commonly due on the borrower’s next payday. The Consumer Financial Protection Bureau describes payday loans as short-term, high-cost loans that are often for $500 or less, although limits and availability depend on state law.
Some lenders now offer installment loans instead. Rather than requiring one large payment, an installment loan divides the balance into several scheduled payments. This may make repayment more manageable, but a longer term can also increase the total interest paid.
A fast cash loan should therefore be evaluated by its total cost – not simply by how quickly the money may arrive.
How Online Fast Cash Loans Work
Applying for an online cash loan is usually more convenient than applying at a storefront. The entire process may be completed through a lender’s website or mobile platform.
Completing the Online Application
The application normally asks for basic personal, employment, income, and banking information. A lender may request your full name, residential address, identification details, monthly income, employer information, bank account number, and contact details.
Many applications can be completed in several minutes. However, completing an application does not guarantee approval. The lender may still need to confirm your identity, income, bank account, and ability to meet its eligibility requirements.
Be cautious when a website describes a form as a loan application but actually operates as a lead generator. A lead generator may send your information to several lenders or marketing companies rather than lending money directly.
Reviewing the Loan Offer
When an application is accepted, the lender should provide a loan agreement showing the amount borrowed, finance charge, annual percentage rate, payment schedule, due date, late-payment policy, and total amount owed.
Read this agreement carefully before accepting the money. Do not rely only on advertisements that promote “quick approval” or “cash today.” The written agreement determines what you will actually have to pay.
Receiving the Funds
Approved funds may be transferred electronically to the borrower’s bank account. The timing depends on when approval occurs, the lender’s processing system, the receiving bank, bank cut-off times, weekends, and public holidays.
A lender advertising an instant decision is not necessarily promising an instant bank deposit. Approval speed and funding speed are two different things.
What Do You Need to Qualify?
Eligibility requirements differ among lenders, but applicants are commonly expected to be at least 18 years old, have an active bank or credit union account, receive regular income, and provide valid identification and contact information.
Some lenders accept applicants with limited or imperfect credit. That does not mean every application will be approved. A lender may still review income, banking activity, existing debt, payment history, or other financial information.
Before applying, prepare accurate information about your income and regular expenses. Never exaggerate your earnings or provide false employment details. Incorrect information can lead to rejection and may create more serious problems if a loan is issued based on misleading information.
You should also estimate how much money will remain after your next paycheck arrives. If repaying the loan would leave you unable to pay rent, food, utilities, transportation, or other essential expenses, the loan may only move the financial emergency to a later date.
How Much Does a Fast Cash Loan Cost?
The cost is one of the most important factors to examine. A small finance charge may appear affordable when expressed as a dollar amount, but it can represent an extremely high annual percentage rate when the repayment period is only two weeks.
The Federal Trade Commission states that payday lenders commonly charge between $10 and $30 for every $100 borrowed. A fee of $15 for each $100 on a two-week loan is equivalent to an APR of approximately 391%.
For example, suppose you borrow $300 and the lender charges $15 for every $100. Your finance charge would be $45, making the total repayment $345.
That may appear manageable until the full amount is deducted from your next paycheck. If you cannot afford the payment and renew, refinance, or replace the loan, additional charges may accumulate.
Before accepting an offer, ask one practical question: How many dollars will leave my bank account from the day I borrow until the debt is completely repaid?
Include application fees, finance charges, interest, late fees, unsuccessful-payment fees, optional services, and possible bank overdraft charges in your calculation.
Are No-Fax Payday Loans Really Paperless?
The phrase “no-fax payday loan” became popular when traditional lenders required borrowers to fax pay stubs, identification documents, or bank statements. Modern online lenders can often verify this information electronically.
No-fax does not necessarily mean no documentation. You may still be required to upload a photograph of your identification, connect a bank account, submit a digital bank statement, or provide proof of income.
A legitimate lender should clearly explain what information it collects and how that information will be used. Review the website’s privacy notice before submitting your Social Security number, bank credentials, or identification documents.
Avoid lenders that request payment through gift cards, cryptocurrency, wire transfers, or other difficult-to-reverse methods before releasing a loan. An upfront request for money in exchange for “guaranteed approval” is a major warning sign.
How to Compare Fast Cash Lenders Safely
Do not select a lender based only on the largest advertised amount or fastest promised approval. Compare the total repayment amount, APR, payment dates, number of payments, late-payment policy, customer support options, and authorization to operate where you live.
The Consumer Financial Protection Bureau recommends considering the cost, repayment ability, available alternatives, and safety of your personal information before taking out an online payday loan.
Check whether the company identifies its legal business name, physical address, telephone number, licensing information, and loan terms. Search the company name alongside words such as “complaints,” “scam,” or “license.”
Do not assume that a professional website guarantees a trustworthy lender. Fraudulent websites can copy logos, testimonials, and legal language. Avoid any lender that pressures you to act immediately or refuses to provide the full agreement before you accept the loan.
You should also limit the number of websites receiving your information. Submitting applications through several lead-generation forms can result in repeated calls, emails, text messages, and wider distribution of sensitive financial data.
What Happens When Repayment Is Due?
Online lenders commonly ask borrowers to authorize an electronic withdrawal from a checking account. This authorization is often known as an ACH authorization.
On the agreed payment date, the lender may attempt to withdraw the principal, interest, and applicable fees. If the account does not contain enough money, the transaction may fail and the borrower could face charges from both the lender and the bank.
The CFPB explains that consumers may revoke an ACH authorization and can ask their bank or credit union to stop an electronic debit. Stopping the debit does not cancel the debt, however; the borrower remains responsible for arranging another lawful payment method.
Review the repayment instructions before the due date. Some agreements may handle renewals or extension fees differently from full repayment. Contact the lender early when you expect a problem rather than waiting until the withdrawal fails.
Alternatives to Consider Before Borrowing
A fast cash loan is not the only way to handle an emergency. Contact the company you need to pay and request an extension, hardship plan, split payment, or different due date. Medical providers, utility companies, landlords, and service providers may be willing to arrange payments when contacted early.
You can also ask your bank or credit union whether it provides a small-dollar emergency loan. Federal credit unions may offer Payday Alternative Loans, commonly called PALs, with regulated loan amounts, terms, and fees. These products are intended to provide a lower-cost alternative to traditional payday lending.
Other possibilities include an employer paycheck advance, assistance from a local nonprofit, a carefully planned credit card purchase, selling an unused item, borrowing from family under a written repayment agreement, or temporarily reducing nonessential spending.
Each option has advantages and risks. The objective is not merely to obtain money quickly, but to solve the emergency without creating a more expensive financial problem.
When Does a Fast Cash Loan Make Sense?
A short-term loan may be considered when the expense is genuinely urgent, the lender is properly authorized, all costs are disclosed, no affordable alternative is available, and you are confident that repayment will not interfere with essential bills.
It is usually a poor choice when the money will be used for gambling, entertainment, unnecessary shopping, another loan payment, or recurring monthly expenses. Repeatedly borrowing to cover ordinary bills is a sign that the underlying budget needs a longer-term solution.
Avoid borrowing when the repayment plan depends on taking out another loan. A loan that can only be repaid through refinancing is unlikely to provide meaningful financial relief.
Getting a fast cash loan now may appear simple, but responsible borrowing requires more than completing a quick online form. Compare multiple options, verify the lender, calculate the total repayment, protect your personal information, and make sure the payment will fit within your next budget.
Never assume approval or same-day funding is guaranteed. Most importantly, explore payment arrangements, credit union loans, employer assistance, and other lower-cost alternatives first. When borrowing is unavoidable, accept only the amount you genuinely need and choose a repayment schedule you can realistically complete. Review every fee before signing and keep a copy of the agreement for your records.